Next Post

NEXT POST WILL BE PUBLISHED ON OR
AROUND June 7, 2016.

SHOWN TO THE RIGHT, ARE THE CONTENTS OF THE 11/27/12 LETTER SIGNED BY PRIORITY ONE CREDIT UNION PRESIDENT, CHARLES R. WIGGINGTON, SR. IN COMPLIANCE TO THE TERMS OF SETTLEMENT AGREED TO BY THE CREDIT UNION AND A MEMBER WHO SUED THE CREDIT UNION, ALLEGING THEIR WILLFUL VIOLATION OF THE PRIVACY ACT.

Our Readership: U .S., Ukraine, Russia, France, Germany, United Kingdom, Poland, Malta, Malaysia, Laos, Canada, Greece, Turkey, Sweden, China, Taiwan, Hong Kong, Isle of Man, Portugal, Morocco and more!

Translate

SEARCH THIS SITE

Showing posts with label Annual Reports. Show all posts

Wednesday, July 29, 2015

Defining What's Normal, Part 3 of 3


During the month of July, Priority One Credit Union's attorney filed yet another motion, this time contesting the reasons filed by Turner, Warren, Hwang, and Conrad seeking the dismissal of the credit union's counter-lawsuit. 

The trial of the lawsuit filed by CUMIS, accusing Turner, Warren, Hwang, and Conrad of breaching its agreements with Priority One Credit Union during the years of 2008, 2009, 2010, 2011, 2012, and 2013, has not yet begun. Presently, Turner, Warren, Hwang, and Conrad and Priority One Credit Union remain locked in litigation as Turner, Warren, Hwang and Conrad seeks dismissal of the counter-complaint filed by Priority One this past.

Additionally, the court has not yet made a decision regarding the motion filed by Priority One's attorney, John C. Steele, requesting consolidation of the lawsuits filed by CUMIS; Turner, Warren, Hwang and Conrad; and the cross-complaint filed by the credit union. In the meantime, the bankruptcy filing by former AVP, Lynnette Fortson, who is accused of stealing $1 million in cash from the vault of the Los Angeles branch, remains in review.

If litigation seems chaotic, it's because it is. Nowadays, Priority One is characterized more by its legal entanglements than for business. This change in standing began in the years following January 1, 2007, the date Charles R. Wiggington, Sr. began his appointment as President. 

Despite the onslaught of lawsuits filed by and against the credit union, this past May, President Wiggington entered into yet another of his verbally and completely fictitious campaigns declaring that business is good and improving. The problem with the President's periodic proclamations is that they're never true and constitute pure conjecture. He could lend tremendous credibility to his statements if he would support them with actual documentation but he doesn't because these sporadic efforts to save face are untrue. Unfortunately, for the disastrous President, the credit union's quarterly Financial Performance Report ("FPR") and monthly income statements/Balance Sheets all omit anything that could be interpreted as a resurgence in business. What's more, as members and readers of this blog may have discovered, President Wiggington has yet to release copies of the 2014 annual report which for years, was distributed to attendees of the annual meeting conducted each May 27th at the South Pasadena branch. What's more, if you'll visit the credit union's website, you'll note that the President has not allowed publication of the report. HIs censorship and control of the credit union's reports suggest that President Wiggington has much to hide.

The President's efforts to paint a rosy picture of Priority One's financial standing and performance was aided during the month of May, when Robert West, the Director of Employee Services composed an online review praising  HigherUp's, Rocket Solution.  Rocket Solution is an analytical program. According to Mr. West, Rocket Solution has helped the Human Resources Department's refine its processes and extrapolates employee data which is analyzed and used to improve the credit union's bottom line. It is hardly coincidence that Mr. West's review comes at a time when the credit union is in desperate need for positive publicity though the Director's efforts are typically feeble, obvious and fail to deter attention away from the credit union's all too public reputation. 

Before presenting excerpts from Mr. West's review, we'd like to revisit some past incidents involving Mr. West which attest to his character and validate whether or not Mr. West has ever contributed to improving the credit union's bottom line, promoted employee morale, or served to impel growth and development of new business.  


Over the years, some of our posts have elicited negative comments about Robert West. The Director of Employee Services has been a staple of the credit union for several years though his greatest promotions came via his friend, President Wiggington. In the years before January 1, 2007, the date Charles R. Wiggington, Sr. was appointed President, Mr. West served as the credit union's sole Trainer and later, under President Wiggington, as Manager of Training and Education. Prior to 2007, he would periodically describe Priority One as a place where "the devil lives." A rather harsh and judgmental declaration by an officer of the credit union. 

In 2006, he spent months writing a self-help book which was not related in anyway to his position as Trainer though he worked on the book during business hours. In 2006 and again in 2007, he was periodically seen by employees and officers, sleeping at his desk. You can read more about some of Mr. West's other antics at Robert West.

In 2009, President Wiggington asked that Mr. West rewrite the credit union's mission statement. The President stated that the statement composed under his predecessor failed to express his vision for the credit union and its relationship to its members. In 2009, Mr. West's revamped statement was unveiled during the May 2009 Annual Meeting conducted in Pasadena, California. The statement, shown below, was copied from the credit union's Facebook page.

Our mission: "To help our member-owners and employees achieve financial fitness. We are committed to providing quality products and services that help you win with money."  

We must point out that the Mission Statement published in 2009, differed slightly from the its current version and included language which promised to show members and employees how to "win with money." Branch closures, a decline in the amount of net income, and a 5-year wage freeze prompted President Wiggington to amend the statement in early 2014. 

FOOT IN MOUTH
Though President Wiggington's failures, abuses and violations of state and federal laws are well documented, he has always found an avid and unwavering supporter in Mr. West. As we've reported in 2010, during all-staff meeting conducted at Almansor Court in Alhambra, California, Mr. West stood before a room full of employees and chastised the President's critics, labeling them "haters". During his chastisement, he attempted to elicit pangs of guilt from targeted employees by reading the following verse: 

"If your enemy is hungry, feed him; if he is thirsty, give him something to drink. In doing this, you will heap burning coals on his head." - Romans 12:20

Not surprisingly, his manipulation of Biblical scripture back-fired and served to increase dissension between staff and management. Though he had hoped to subjugate employees using amateur manipulative tactics, following the meeting, most of his audience exclaimed that they did not know what the verse he read meant while others admitted to listening to his spiel. 

2008

In 2008,  a member visited the credit union, leaving a baby she was taking care of, locked in her car in the visitor parking lot located at the South Pasadena branch. Though she was advised by employees that the baby was crying the member replied that she would return to her car in a few minutes. Because President Wiggington was away from the branch for the day and because Rodger Smock could not be located, an employee informed Mr. West that a baby had been left locked in a car. He immediately ordered that the police be called. Police arrived and arrested the member while firemen extricated the baby from the automobile. 

The following day, upon being advised of the incident. President Wiggington exploded demanding the names of the employees who called the police. When told that they obtained from Mr. West to call the police, the President threatened each employee with termination should they ever choose to report a member to the police. Mr. West denied ever having instructed the employees to call the police. 

2010

In August 2010, then COO, Beatrice Walker, took control over Human Resources. At the time, she revealed she intended to force aged Executive Vice President, Rodger Smock, into retirement because in her opinion, he was "lazy" and "overpaid". She also disclosed she intended to terminate Robert West who she described both "unnecessary", "overpaid" and ineffective as a trainer. 

Because much of his power had been transferred to Ms. Walker by Board Chair, Diedra Harris-Brooks, President Wiggington panicked because he knew he would be unable to retain the employment of either Mr. Smock or Mr. West who were the only two ethically pliable supporters of his regime. However, Ms. Walker's plans were derailed when the then Valencia Branch Manager visited the South Pasadena branch and filed a verbal complaint with Esmeralda Sandoval, alleging that Ms. Walker had: 
  • Estranged the Branch Manager from her staff and other Branch Managers
  • Sexually harassed and stalked her
  • Created a hostile working environment; and 
  • Subjected the Branch Managers to different standards than those set for other managers
In September 2010, the President and Mr. Smock drove to the Valencia branch to inform the Manager that her branch was scheduled to close at the end of October 2010. After advising her of the impending closure, he asked her to elaborate on her complaint against Ms. Walker. At the end of the meeting, he turned to Mr. Smock and said he was going to remove Ms. Walker from oversight of the Human Resources Department. President Wiggington also informed the Branch Manager that he would offer her a post as Assistant Branch Manager at the Burbank office though her salary would be reduced "slightly." 

Three days later, the president issued a notice on the credit union's Intranet announcing that Robert West would not serve as Director over Human Resources despite the conspicuous fact Mr. West was wholly unqualified to head the department. The reason why Mr. West was placed over Human Resources is quite absurd. At the time, Rodger Smock, the Director informed the President that he did not want any involvement in the Valencia Branch Manager's complaint. He felt that his involvement could provoke Ms. Walker who he knew was planning to terminate him. 

Mr. West was appointed Director and given the responsibility to handle the complaint against Ms. Walker. Mr. West's ineptitude was quickly revealed because he continually had to confer with Mr. Smock to learn how to proceed with the complaint. 

At the end of September 2010, the Branch Manager was called on her credit union cell phone by then Human Resources "clerk", Esmeralda Sandoval and advised that she had eight (8) hours in which to either accept the credit union's offer to work in the Burbank office in the capacity of Assistant Branch Manager or accept the credit union's severance package. At the end of the day, the Branch Manger called Ms. Sandoval and told her she would accept the severance package. Ms. Sandoval informed the Branch Manager that the credit union would require a letter stating her decision. The Manager submitted a letter to Ms. Sandoval, via email. The letter disclosed that she would accept the severance package and that her final date of employment would be October 31, 2010. 


Several days later, Ms. Sandoval called the Branch Manager and informed her that she would have to work until November 15, 2010, to be eligible for the severance package. The Branch Manager reminded Ms. Sandoval that she had never stated that her final day of work would be November 15, 2015. Ms. Sandoval at first lied and said she had provided the Branch Manager with the date, however, Ms. Sandoval's dishonesty was proven when the emails sent to the Branch Manager regarding the matter all omitted a required last day of employment. The Branch Manager was afterwards contacted by Robert West who told her she must either work until November 15, 2010 or forfeit her severance package. The Branch Manager responded by sending Mr. West the following letter:

Mr. West conferred with the President and Ms. Walker, who in turn contacted Board Chair, Diedra Harris-Brooks. Mrs. Brooks contacted the credit union attorney and it was decided that credit union due to its own negligence, must provide the Branch Manager with the severance package that had been offered by the careless, Esmeralda Sandoval. Following the decision to reinstate the offer, Mr. West returned to his role as trainer and Mr. Smock resumed his capacity as Director over Human Resources. 

Mr. West Writes a Review


Clearly Priority One is not providing member's convenience, efficiency or financial services that are so affordable that they did not entice approximately 4,000 members to retain membership.  


Now as you read Mr. West's review, not that he fails to draw a correlation of how HigherUp's Rocket Solution will provide Priority One's Human Resources Department "new business insights. The fact that Human Resources is now allegedly "working faster and more strategically to improve the company's bottom line" is unaccompanied by actual evidence, like the credit union's own reports proving that Priority One's bottom line has been improved. 

Mr. West's review is permeated by a whining tone, describing his personal frustrations as he tried to juggle the use of three different programs with each requiring the use of its own password. We certainly feel for Mr. West and the terrible plight he must have undergone. We'd like to address some of the statements contained in his review. 
  • On January 1, 2007, Priority One's membership approximated 30,000. Eight years after Charles R. Wiggington, Sr. was appointed President, membership has dropped to approximately 26,000. That's a loss of 4,000 members over an 8 year period. 
  • Prior to January 1, 2007, the date Charles R. Wiggington, Sr. became President, the credit union employed more than 150 full-time employees and only periodically hired temporary staff. 
  • Prior to January 1, 2007, Priority One the following branches:
Worldway Branch
Los Angeles 
Van Nuys Branch
Valencia Branch
South Pasadena Branch
Redlands Branch
Riverside Branch


On the day Charles R. Wiggington began serving as President, the Marina Del Rey branch had already closed because the postal service intended to use the space occupied by that office. Other branch closures and openings, ordered by President Wiggington include:


Redlands Branch closes September 2010
Valencia Branch closes October 2010
Riverside Branch closes April 2011
Santa Clarita Branch opens February 2012
Airport Branch closes December 2013
Santa Clarita branch closes January 2014.

From an economic and budgetary point-of-view, Priority One's opening and closing of branches over the last eight years constitutes poor, actually, horrendous planning and was both fiscally irresponsible and detrimental to the credit union's bottom line. 

If the implementation of HigherUp's analytical program is intended to improve Priority One's bottom-line than one has to ask why was Priority One's net income increasing annually under President Wiggington's predecessor and why has it dropped by more than $18 million since January 1, 2007, the date Charles R. Wiggington, Sr. began serving as President? 

We extracted the following information from NCUA.org:


The current Board of Directors along with President Wiggington have proven they possess an undisciplined proclivity for spending and wasting credit union funds. This is partially attested to by the fact that currently, Human Resources employs three officers when prior to January 1, 2007, the department was wholly under management of then Vice President of Human Resources, Rodger Smock. Nowadays, the small and insignificant credit union is staffed by Mr. Smock, Mr. West and Employee Services Manager, Esmeralda Sandoval.

According to Mr. West, he was "frustrated with our old systems, which were time-consuming and difficult to manage. To get to even the most basic employee information, I had to access three different vendors’ systems with multiple passwords and complex authentication. And none of the systems could talk to each other. If I wanted to access and combine data from our different payroll, benefits, applicant tracking, and time and attendance systems – I was out of luck.”


Of course Mr. West was frustrated. . He holds a position which he is ill qualified to serve in. In 2011, he was appointed to serve as Director of Human Resources without possessing any experience, an education, or skills in anything related to Human Resources. His appointment was not motivated by either his qualifications or need. Mr. West was appointed as a result of cronyism. It is his "friendship" and blind loyalty to the President that has secured his continued employment. He is clearly dispensable and wholly unnecessary to the credit union's deteriorating infrastructure.  

Apparently, the "Director" of Employee Services is easily frustrated. It is not uncommon for employees of many companies to use more than one program to process their work and certainly having to use more than one password is neither challenging or frustrating unless of course, you're Mr. West. We also don't understand how Human Resources, a department staffed by three officers, can't seem to handle managing Priority One's three remaining branches and a staff which Mr. West wrote, employs 50 full-time employees and 14 part-time employees What would Mr. West have done had he worked in the department prior to January 1, 2007, when the credit union had many branches and employed more than 150 full-time employees. Maybe the problem is that Robert West doesn't possess the skills needed to multi-task or he lacks the ability to expertly prioritize. 


THE TRIAL THAT WOULDN'T START


During the month of June, Priority One's attorney, John C. Steele, filed a motion refuting Turner, Warren, Hwang, and Conrad's reasons asking the court to dismiss Priority One's counter-lawsuit against their former external auditor.

The long list of pre-trial conferences clearly indicates that Priority One's legal expenses in 2015, must be astronomical adding to the more than $500,000 spent on litigation during the years of 2010-2013. Nowadays, Priority One is defined by its unending legal problems. 

We're recently wondered about the abilities of CUMIS' officers to make sound decisions as their alliance to Priority One Credit Union is not only illogical, it seems a horrendous business decision and gamble. That said, last month one of our readers posted the following comment which aptly and in great detail, describes the reason why CUMIS may be suing Turner, Warren, Hwang, and Conrad and what may occur should CUMIS lose its lawsuit:

June 24, 2005

Look ... I don't see Wiggington lasting 12 months.

Some points & issues to clarify. CUMIS (the insurance & bonding company) paid the claim for dishonesty... that's the insurance they provide. For paying the claim, the CU gives the bonding company the 'right of subrogation' .... this means it gives the insurance company the right to go after the individual(s) that were responsible for the loss.


By extension, the insurance company is trying to minimize its losses by looking at other potential sources for getting their money back. Assuming the responsible person(s) do not have $1,000,000 anymore they will simultaneously look elsewhere.


So, they are looking for 'Big Pockets'....one of which is TWHC CPA firm. The Board & Wiggington were pointing their fingers at TWHC for not discovering the defalcation and the 'embezzler'for dishonesty.


In reality they should being pointing at themselves in the mirror. They are the problem.


It's going to get real messy when public filings start coming through.


In addition, it is very possible that Wiggington will then be placed on CUMIS' "BLACK LIST" of non-insurable risks. Each employee or official of a federally insured financial institution has to be "bondable". Wiggington's record will become more public and other policyholders (credit unions) will see the risk that the insurance company is continuing to insure.....they are the ones paying Wiggington's claims.... they will want that to cease.

Wiggington will get the dreaded letter & phone call in the next year, for sure & he's gone. A week or two before official notification to Wiggy, the Feds and State Examiners will all converge on the credit union ..... don't you think they will count every penny?

CUMIS provided a report in which their "expert" asserts that Turner, Warren, Hwang and Conrad have failed to adhere to established auditing practices in the years 2008, 2009, 2010, 2011, 2012 and 2013. It appears, CUMIS is attempting to strengthen its position buy inducting the participation of the credit union whose counter-lawsuit will serve to further impugn Turner, Warren, Hwang, and Conrad's public reputation and abilities. What is interesting is that without the findings of CUMIS' expert, Priority One may never have realized that their former external auditor had allegedly violated auditing practices. As usual, the bad folks at Priority One Credit Union seemed oblivious of the integrity of work being performed by their external auditor. It's this same lackadaisical problem that may have resulted in the theft of more than $60,000 in 2009, perpetrated by a former receptionist; and the 2010-2012 thefts totaling more than $1 million in cash, allegedly absconded by a now former AVP.  Something is sorely amiss at Priority One. Its Supervisory Committee have proven themselves incapable of protecting credit union assets. The President and the people who oversaw operations* during the years of 2009 through 2012 have evidently failed to ensure the protection of Priority One's assets and have proven quite incapable of protecting Member funds.   

*2007-June 2009: Operations was managed by EVP, Rodger Smock
June 2009-July 2011: Operations was overseen by COO, Beatrice Walker
July 2011-December 2012: Operations was overseen by CLO, Cindy Garvin
January 2013-Present: Yvonne Boutte currently serves as VP of Operations

In David Morrison's article, "$1M Vault Pinch Hits Priority One" which appeared in the March 07, 2015 publication of the CU Times, the author states that in their lawsuit, CUMIS accuses Turner, Warren, Hwang and Conrad of negligence in auditing the credit union's financial records and that they "should have known that [Lynette] Fortson [the AVP] was employed at the Los Angeles County Branch and that one of her duties was to perform reconciliation for that branch." CUMIS also told the reporter that Turner, Warren, Hwang and Conrad "had never opened the vault, counted the vault cash, reconciled the counted vault cash to the general ledger account or reviewed the balancing sheets prepared by Fortson during the course of their reconciliation of cash accounts" and if they had, Turner, Warren, Hwang and Conrad would have discovered the "fraud and embezzlement scheme." 


We recently spoke to a former officer of the credit union who informed us that in the years before Charles R. Wiggington, Sr. was appointed President, the Supervisory Committee regularly visited branches to count vault cash. The end of this practice by the Supervisory Committee seems part of a common phenomena occurring at the credit union. In 2007, Charles R. Wiggington, Sr., refused to review a batch of sample ballots which if he had, he might have noticed that member social security and account numbers were printed on the front exterior side of the the envelopes. At the time, he refused to review these because in his words, "I'm President, I don't do that!"  The fact that in 2009, the credit union employed an internal auditor and COO proved insufficient to discover that a receptionist was pillaging funds from member accounts. 


Due to the length of Attorney John C. Steele's response, we are only publishing the more relevant points of his rebuttal. 


This is the first reference in the long record of documents filed with Superior Court that finally provide more specific detail about the thefts which occurred at the Los Angeles branch during the years of 2010 through 2012. As we've disclosed in previous posts, CUMIS has stated in its initial filing that the thefts began either in "early" or "late" 2010. We find it odd that following an extensive investigation by its "experts" that they could not pin point a more specific or actual date when the internal robberies began prompting us to wonder if the amount of thefts exceed the $1,005,000 CUMIS concludes was stolen. More importantly, did the robberies begin prior to 2010 and possibly on a date before Turner, Warren, Hwang and Conrad were hired. 

In 2009, Turner, Warren, Hwang and Conrad were hired to conduct an extensive audit of the Los Angeles branch's records. At the time, the audit was reported after a member complained that money had been taken from her more than $11,000 IRA leaving a balance of less than $5,000. The audit proved that more than $60,000 were embezzled by a former receptionist who pillaged member accounts and with the assistance of friends and family, withdrew embezzled funds from an ATM located in the city of Long Beach, California. During the audit, then AVP, Lynnette Fortson sat alongside Terry Nabors, the auditor from Turner, Warren, Hwang and Conrad. She remained in the office with him for the three weeks during which he audited her office's records. President Wiggington was well aware that she forced her inclusion in the audit but was apparently unconcerned by its inappropriateness.  Why would the AVP deem it necessary to sit alongside the auditor if she, herself, was not auditing records? We are suspicious of her motivation for remaining in the office with Mr. Nabors during the three weeks in which he reviewed records. 


Attorney Steele states that on December 5, 2014, Turner, Warren, Hwang and Conrad sued Priority One's refusal to pay the outstanding balance of $68,299.79 due for the report created by Turner, Warren, Hwang and Conrad from their March 2013 investigation of the Los Angeles branch's records. 

The cross-complaint filed by Priority One Credit Union not only contests payment of the unpaid balance which Attorney Steele has described as "ridiculous" but sues Turner, Warren, Hwang and Conrad for providing inaccurate reports to the credit union for the years of 2008 through 2013. It should be deemed nothing less than outstanding and in Mr. Steele's words, "ridiculous", that Priority One Credit Union never realized that the reports provided to it by Turner, Warren, Hwang, and Conrad were inaccurate and produced out-of-compliance with established auditing protocols. 

Furthermore, Attorney Steele states that Priority One was unaware of the alleged negligence committed by Turner, Warren, Hwang and Conrad until April 24, 2015, when they received a report produced by CUMIS' "expert" and which asserted numerous alleged violations committed by the credit union's external auditor. 


Again, Turner, Warren, Hwang and Conrad are innocent until proven guilty. Subsequently, Mr. Steele's statement that the external auditor "failed to comply with the terms of its contracts for years" constitutes a mere allegation. 


Attorney Steele, declares that Turner, Warren, Hwang, and Conrad's lawsuit against Priority One for its failure to pay $68,299.76 due the external auditor failed to "acknowledge" or mention, that it served as Priority One's external auditor from 2008 through 2013, during which it provided year-end audits. If Attorney Steele is inferring that Turner., Warren, Hwang and Conrad purposely avoided disclosing this fact, it seems irrelevant since they are demanding payment from the credit union for services rendered in March 2013 and no other year. 

Attorney Steele continues, stating that The $168,299.79 initially charged by Turner, Warren, Hwang and Conrad is nothing less than "ridiculous"? Is there any documented evidence showing that Priority One contested the charge in 2013, 2014 or at the start of 2015? Evidently, Priority One did not find the charge ridiculous, otherwise why did they pay $100,000 of the total amount due to Turner, Warren, Hwang and Conrad. 

Attorney Steele admits in his filing that Priority One was ignorant of the alleged violations committed by Turner, Warren, Hwang and Conrad until on or about April 24, 2015 when they received a report provided to them by CUMIS' "expert" whose investigation showed that the report produced from the external auditor's February 2013, investigation was so poorly written that it had to be rewritten by attorneys so it could be submitted to CUMIS along with Priority One's claim for $1 million.

 What seems odd is that during the 26 months which transpired between February 2013, the month when Turner, Warren, Hwang and Conrad conducted its audit; and April 24, 2015, the date when the credit union received CUMIS' report documenting the allegations against the external auditor, that Priority One's President, its Board of Directors, and its Supervisory Committee never realized that Turner, Warren, Hwang, and Conrad allegedly provided inaccurate end-of-year reports for 2008, 2009, 2010, 2011, 2012, and for the report provided in 2013. So when is Priority One held responsible to ensuring that information they receive is verified to be correct? And why didn't Priority One ever realize that any of the numerous reports provided to them by their external auditor contained erroneous information? 

And why did Priority One refuse to pay the outstanding balance due to Turner, Warren, Hwang, and Conrad in 2013, 2014, and part of 2015 if they didn't know about the external auditor's alleged violations until April 24, 2015? Could it be that Priority One refused to pay the bill because they are unable to?  In 2010, now former CFO, Saed Raad, instructed his staff in the Accounting Department not to pay vendor bills for at least 3 to 4 weeks after these are received.  Priority One is a credit union whose coffers have been heavily taxed by expenditures that are unrelated to business including more than $500,000 spent on legal fees during the years of 2010 through 2014. 

Mr. Steele places entire blame on the external auditor because of their failure to perform audits compliant to its contracted obligations but the fact remains that no one at the credit union- not the self-proclaimed financially savvy President, the Board of Directors or the Supervisory Committee ever took note that any of the end-of-year reports provided to them contained egregious violations of the agreements ratified between the external auditor and the credit union. So when is Priority One deemed responsible for the years of failures committed by its President and two governing bodies? 


Attorney Steele's argument is that Turner, Warren, Hwang and Conrad's did not perform annual audits commensurate with the terms of the agreements entered into with the credit union. He alleges that as a result of this, Priority One was forced to rehire Turner, Warren, Hwang, and Conrad who conducted an investigation of the Los Angeles branch's records in March of 2013. 

Attorney Steele's key points in his conclusion are:
  • Turner, Warren, Hwang and Conrad failed to adhere to the terms of their agreement entered into with Priority One Credit Union
  • He accuses Turner, Warren, Hwang and Conrad of filing a motion whose focus is the date when the embezzlement took place
  • Turner, Warren, Hwang and Conrad allegedly breached their agreements and provided inaccurate reports to the credit union in the years 2008, 2009, 2010, 2011, 2012 and 2013. 
  • Turner, Warren, Hwang and Conrad "actively concealed its breach of contract"; and
  • As a result of their alleged concealment, Priority One could not have known prior to April 2015, that Turner, Warren, Hwang and Conrad had violated its agreements with the credit union
Attorney Steele will have to prove that Turner, Warren, Hwang and Conrad purposely concealed the breaches they are how accused of committing. He is accusing the external auditor of knowingly if not intentionally, violating its agreements entered into with Priority One in 2008, 2009, 2010, 2011, 2012, and 2013. Are we then to believe that Turner, Warren, Hwang and Conrad, a company with an impressive portfolio of credit union industry clients. would single out Priority One, a credit union with a horrendous public reputation and led by a President whose horrendous performance is marred by numerous failures, abuses of authority, egregious violations of state and federal laws, and last but not least, a well documented record of numerous security breaches of which the $1 million theft is but one?

The fact is, under Charles R. Wiggington, Sr., internal thievery on a massive scale has become common place at Priority One Credit Union. So how did one AVP enter the Los Angeles branch vault, unaccompanied and in defiance to double-custody and in violation of the credit union’s security protocols and over a 24-month period, steal more than $1 million? It’s mind-boggling.

CONCLUSION

There isn't any evidence presented by either side that might allow us to guess who could potentially win their lawsuit. CUMIS hopes the court will find Turner, Warren, Hwang, and Conrad guilty of violating it's agreements with Priority One and of conducting audits that proved subpar and out of compliance with standard auditing procedures. They are also requesting the court order Turner, Warren, Hwang and Conrad to pay $1 million plus any other fees the court deems appropriate. 

What CUMIS and the credit union are not alluding to in their complaints is that during the thefts occurred, Priority One had a President, a Board of Directors, a Supervisory Committee, an Accounting Department and three different offices who oversaw operations, yet inexplicably all failed to realize cash was being taken from the vault of the Los Angeles branch.

CUMIS and Priority One make reference to Lynnette Fortson, the former AVP accused of embezzling $1 million in cash but we've yet to discover how she was able to enter a branch vault by herself and in defiance of credit union banking policy which stipulates double-custody when entering the vault; and how she was able to walk out with $1 million in cash over an approximate 24-month period. The fact she succeeded in perpetrating embezzlement on such a grand scale points to failure on the part of the credit union and its alleged security protocols designed to protect credit union assets. No matter how much CUMIS may wish to hold Turner, Warren, Hwang and Conrad accountable for the theft of $1 million, the fact is, the external auditor had no involvement in the physical removal of cash.

Priority One should be held accountable for failing to detect any of the thefts. Based on their attorney's disclosures, Priority One relied solely on a single year-end report provided by Turner, Warren, Hwang and Conrad to assess the effectiveness of its own security. Apparently, Priority One never verified the evidence used by the external auditor to arrive at the conclusions contained in their reports for the years 2008 through 2012. 

Over the past 8-years, the credit union's Supervisory Committee has remained unusually quiet though each year, Supervisory Committee Chair, Cornelia Simmons signs a mundane address written by Rodger Smock and published in the annual report, which repetitiously assures readers that the committee has determined that Priority One is in compliance to all applicable laws and that in her committee's opinion, all is well. In retrospect, since 2009 Ms. Simmons' statements have been proven to be untrue. Ms. Simmons' 2009 address assured readers that the credit union was operating safely yet in that same year, a receptionist absconded with more than $60,000 from the Los Angeles branch. The credit union's current defense indicates that the Supervisory Committee is trying to divert attention away from themselves and placing the entire records of thefts during the period of 2010 through 2012, on Turner, Warren, Hwang and Conrad.

In another matter, in 2014 President Wiggington ordered omission of all references to legal expenses from the credit union's monthly income statement. In 2015, he's ordered that the credit union's 2014 Annual Report not be distributed. His actions suggest he is trying to hide those records that serve to prove Priority One's actual performance versus the tales he loves to tell that allude to non-existent success. Periodically, officers like Robert West try and deter attention away from the credit union's awful public reputation, legal problems, and chronic internal issues. Mr. West's efforts always fail to allay attention from the well-documented fact that since Charles R. Wiggington, Sr. became President, business remains in decline and that lawsuits have been filed each year since 2010, against the once respected credit union. 

In the meantime, we will have to await the results of a trial which will hopefully and finally bring to light the gross incompetence of Priority One's worst and most embarrassing President. For those who are interested, the trial between CUMIS and Turner, Warren, Hwang, and Conrad; and if approved, Priority One's cross-complaint, is slated to take place at Superior Court in Los Angeles on August 24, 2015.  


Friday, October 10, 2014

A History of Failures, Part 1 of 4

It’s Throwback Thursday!


Due to the many comments we received in response to our last post, which alluded to abuses committed in the past by Priority One Credit Union's President, Charles R. Wiggington, Sr., we decided to dedicate this month's publication to some those events. We've selected those incidents and acts which provide the most insight into Charles R. Wiggington, Sr.'s character and ethics and which we believe had the greatest and most destructive impact upon the Credit Union.   

It shouldn't come as a surprise to anyone following Priority One's performance, that September 2014 proved to be another lackluster month for a Credit Union that can't escape its inability to market its products and services at a level required to amass profit, increase membership, and regain its former reputation as a respected and principled organization led by ethical and competent Managers. 

Since being appointed President on January 1, 2007, President Wiggington and his so-called executive staff have failed quite publicly, to develop methodologies that translate into real growth and profit. Since 2010, the Credit Union has struggled to offset its continually increasing overhead and in 2014, is no longer able to provide convenience to Members living and working in many of the communities located within its vast territory stretching from the Santa Clarita Valley in the north to the Riverside/San Diego border, in the South.


The only significant change we noticed during the month of September was that the President abruptly ceased expounding about how his closure of six branches since 2010 were part of an elaborate and well-honed plan guaranteed to  increase business, augment new memberships, and produce real physical growth. We aren't about to hold our breath awaiting fruition of his alleged plan, but his excuse struck as more than a absurd. Since when does eliminating convenience and an inability to provide quality member service reap growth and profit?  

This post contains copies of documentation we've never published previously along with documentation presented in past posts, including biographies written in 2010 by Directors, Diedra Harris-Brooks, O. Glen Saffold, and Richard Hale. The intent of the biographies was to impress and sway voters to re-elect the three incumbents to the Board during the 2010 election. This, by the way, is the election the Board Chair and President disrupted when they tried to exclude a large contingent of Members from voting. The plan was of course foiled when we exposed it on this blog, forcing the Credit Union to conduct a second election. 

The biographies were also published before Priority One was forced to close 6 of 9 branches, before it was forced to terminate a large contingent of full-time employees, replacing them with part-time staff, and before the Credit Union was forced to drastically reduce budgets once spent on successful, prize-winning marketing, advertising and business development. 


Reader comments published in response to our last two posts suggest people have grown weary of the President's and Board Chair's excuses and far-fetched concoctions, created to excuse and even justify the Credit Union's lagging performance and possibly, suggesting that the propaganda churned out by the two officers may have finally and at long last, run its course. 


THE WAYBACK MACHINE


There was a time when Priority One Credit Union could actually afford to publish a monthly and quarterly newsletter. The monthly newsletter ceased publication in 2010, when the Credit Union discovered Members were not reading it.  Publication of the quarterly newsletter continued though abruptly ending in late 2013 and a victim of the President's often ermergent need to reduce spending. In an effort to avoid rumors that the quarterly newsletter was eliminated because the Credit Union could no longer afford to maintain it, the President stated that Members can obtain the latest news about the Credit Union on its droll and often inaccurate, News and Updates page, located on the Credit Union's webpage.  

In Spring 2010 quarterly newsletter, the President declared that Priority One possesses the ability to help every Member achieve financial fitness. 

To place things into perspective, the President's address was published a few months after the Credit Union ended 2009 with -$5,458,432 in losses.  With the assistance of his then ally, COO Beatrice Walker, the President announced Priority One turned a profit during the month of January 2010. The CEO and his COO, lied. What actually transpired was that the President and COO transferred monies from one Credit Union General Ledger, reporting the borrowed monies as profit. Their manipulation of the Credit Union's books had a short-lived effect. By March 2010, the Credit Union's net income was again decreasing and by October 2010, the Credit Union announced it would be closing its Redlands and Valencia branches. On December 31, 2010, the Credit Union reported losses in the amount of -$563,830. 

Despite the dishonest manipulation of the Credit Union's books, President Wiggington arrogantly declared that the Credit Union possessed the ability to help every member achieve financial fitness yet inexplicably and contrary to its own self-promotion, the Credit Union apparently lacked the ability to help achieve its own financial fitness.

In his address, the President also states, “We realize that some of our members may already be financially fit, but still may need assistance”.  The statement is absurd though quite typical of a President who doesn't possess the ability to perpetrate deceptions competently. Why would Members who are financially fit require the assistance of the Credit Union to help them improve their "financial fitness"? A Credit Union whose Net Income has decreased by more than $17 million since January 1,. 2007 is no one's financial fitness center and incapable of helping improve any member's financial status. President Wiggington continues… 


“POCU has anew served referred to as “Balance”, which is a financial fitness program. 

Balance is offered by other Credit Union's and touted as an allegedly "free" financial education and counseling service though in actuality., it is not entirely free to Members who enroll in the program which is designed to help Members introduce control over their finances and achieve their personal financial goals. 


President Wiggington was informed about Balance by Training and Education Manager, Robert West. Mr. West has periodically introduced FREE services to the Credit Union though none has survived the test of time and like his other offerings, Balance ceased to be offered during the same year it was introduced. 


THE PACT


On September 23, 2014, the following comment was posted by a reader of this blog:

"You know who Wiggington is as a man, by his associations. He is close with Smock who is a horrible human being. He is close with West who is no small hypocrite. He’s friends with Henry Justice. It was Wiggington who introduced Henry Justice to the credit union. After Henry Justice refused to surrender pink slips for 5 cars purchased from him by members of the credit union, Priority One had to file a suit in court against Mr. Justice but old wily, street smart Justice filed bankruptcy and said his daughter made off with the money. So Priority One couldn’t touch Henry. In 2009, Henry Justice shows up at the main office with his son and asks to meet with Wiggington. Wiggington comes out and hugs his buddy the thief, at the reception desk and takes him back to the board room. Then they leave the credit union for about 3 hours and have lunch at the Barkley where they talk about reintroducing Mr. Justice to Priority One and again, as a preferred auto broker.

The following week, Henry (Justice) shows up (at the South Pasadena branch) with his son an hands Wiggington a stack of business cards. They leave the office (branch) for about two and a half hours and the next day, Wiggington tells Patti Loiacano that Henry (Justice) is returning to Priority One. Patti reminds him that Mr. Justice (allegedly) stole money and owes the credit union more than $70,000. He (the President) shrugs it off and tells her Mr. Justice will pay back a part of what he owes. He (Henry Justice) pays back about $1300.00 and Wiggington passes out Henry's business cards to every loan officer and processor and tells them they're to promote Mr. Justice's new business as a "preferred broker." The loan people have more character than Wiggington because they all agreed not to promote Mr. Justice because of what he did to the credit union. Then a few days later, a post appears on this blog exposing Wiggington’s new plan. He comes out to the loan department and picks up Mr. Justice’s business cards, he tells the staff not to promote Mr. Justice and he calls Mr. Justice and tells him that if anyone from the board calls him to ask if he’s returning to Priority One that he’s supposed to say no and also say he hasn’t spoken to Wiggington in years. Yep, you can tell who Wiggington is by his associations. 


The Incident


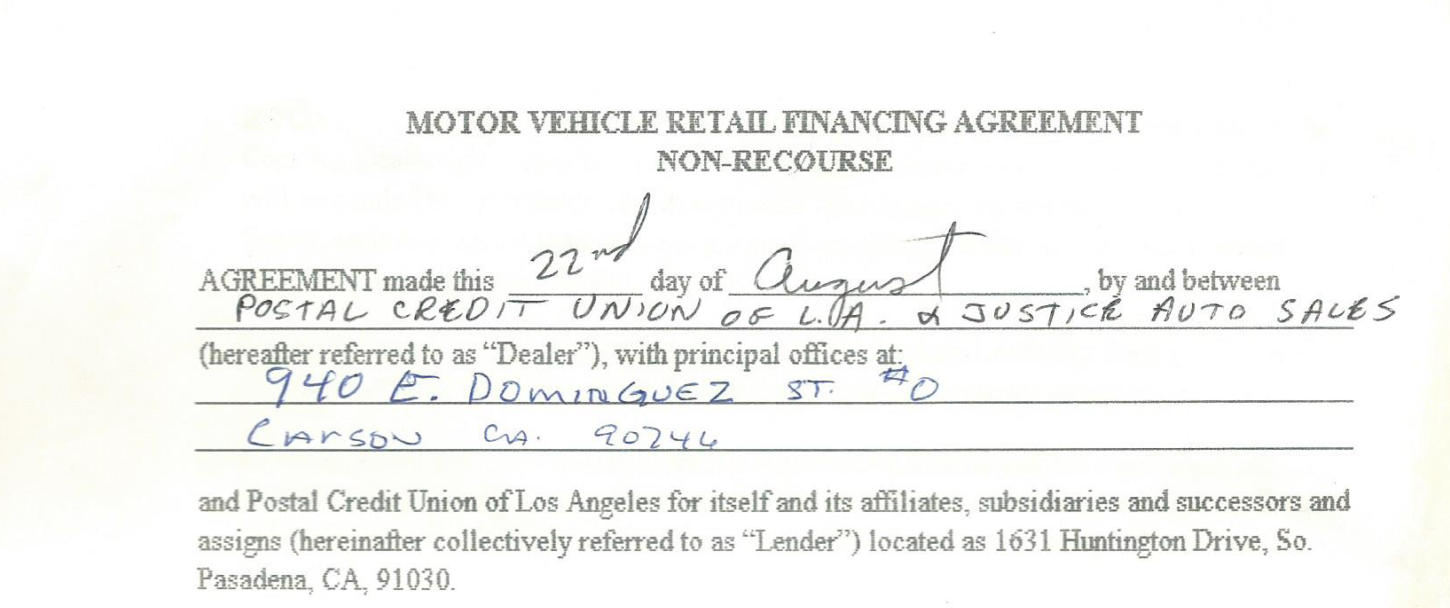
In 1998, Charles R. Wiggington. Sr. introduced his friend, Henry Justice to the Credit Union, intending to promote Mr. Justice's dealership, Justice Auto Sales. What this meant was that Mr. Justice's dealership as a preferred broker.  This meant that representatives of the Member Service and Loan Departments would recommend Mr. Justice's dealership to Members expressing an interest in buying an automobile. In our post, "It May be Fraud to You but not to Charles R. Wiggington, Sr" (Monday, January 26, 2009), we reported that in 2003, Mr. Justice refused to surrender Pink Slips for vehicles purchased by four Members of the Credit Union. Mr. Justice's refusal impeded the Credit Union from registering its name as lienholder of the four automobiles and though the Credit Union had entered into an agreement with Mr. Justice in good faith, the broker refused to surrender the vehicle titles. Due to Mr. Justice's refusal, Members could not obtain Registration Cards from the Department of Motor Vehicles ("DMV")  forcing the Credit Union's DMV Specialists to visit the office of the DMV in Lincoln Park, each month, to obtain a temporary Registration Card so Members could legally operate their automobiles.


To add insult to injury, Mr. Justice filed for bankruptcy. His bankruptcy filing was subsequently approved  by the court, enabling Mr. Justice to avoid repayment of the monies due Priority One. Mr. Justice would later insist that the monies due the Credit Union were absconded by his daughter who had been employed by him at his dealership. 


In 2002, in ongoing efforts to try and acquire the pink slips for each of the four automobiles purchased by Members from Justice Auto, the Credit Union mailed letters, like the one shown below, requesting the dealer provide a copy of the DMV Application so that the vehicles could be properly registered. Mr. Justice chose not to respond. 

08/20/2002

JUSTICE AUTO SALES
20930 BONITA STREET
CARSON, CA 90746 

We have enclosed a check in the amount of $            7344.00        as payment in full for the


following vehicle        1997 HONDA CIVIC                                                                             


Vehicle Identification Number #    2HGEJ6677VH575341                                                     


Being purchased by  LISA M. XXXXXX                             ESTHER C. XXXXXXX                


6412 XXXXXXX AVE                                                        BUENA PARK, CA 90621           


We are now PAPERLESS TITLE. The application to Register New or Used Vehicles with the Department of Motor Vehicles must be Exactly in the name of.

PRIORITY ONE CU

1631 HUNTINGTON DR
S PASADENA CA 91030
                                                    

As Lienholder and the Registered Owner as given above.

To perfect our interest, please send us a copy of the DMV Application to Register the Vehicle.  Thank you for your cooperation.


Respectfully,


Loan Department                        Date: 08/20/2002


In 1998, at the time Mr. Justice was introduced to Priority One by his friend, Charles R. Wiggington, Sr., the dealer entered into a written agreement with the Credit Union, an excerpt of which is shown below. What we find perplexing is that Charles R. Wiggington, Sr.  signed the agreement with Mr. Justice? Doesn't it seem a conflict of interest that Charles R. Wiggington., Sr., a friend of Mr. Justice, signed the agreement which allowed the dealer to become a preferred automobile broker? 


Over the years, Charles R. Wiggington, Sr. has proven an immense inability to comprehend the inappropriateness of his actions. His friend's actions which culminated in bankruptcy, caused Priority One to lose more than $60,000. 

The following letter, dated June 18, 2003, was sent to Priority One by its collection attorney, Bruce P. Needleman. If Mr. Needleman's name sounds familiar, he is the same lawyer who in 2012, responded to a complaint filed at Superior Court in Los Angeles by a Member who alleged Priority One violated the Privacy Act and published information about her automobile loan and her person, on the Internet. Mr. Needleman who was ill qualified to represent the Credit Union in the 2012 lawsuit and was subsequently replaced by an attorney qualified to respond to the Member's complaint. 
Approval of Mr. Justice's bankruptcy should have signaled an end to the business relationship between the dealership and the Credit Union but not so for President Wiggington whose defiance to rules, laws and protocols impel him to seek out what is personally gratifying versus what is good for the Credit Union, Member-Owners, and employees. 

In 2009, Mr. Justice and his son, arrived, unannounced in the lobby of the South Pasadena Branch. They asked the receptionist if they could speak to President Wiggington. The President who will never meet with people who haven't previously scheduled an appointment to meet with him, hurried to the lobby and loudly welcomed Mr. Justice and his son. He afterwards lead the two to the Board Room located at the back of the South Pasadena branch. 

Ensuring security protocols are adhered to is pivotal to any business yet on the day of Mr. Justice's visit, the President invited Mr. Justice and his son into the back offices of the Credit Union's main branch despite the fact Mr. Justice ended his business relationship with the Credit Union just a few years earlier, owing more than $60,000 for vehicles whose titles he refused to surrender. In inviting Mr. Justice to the back offices, the President should absolutely no concern for the well-being of the Credit Union, it's assets and property.  

Three days following Mr. Justice's visit to the South Pasadena branch, President Wiggington informed then Lending Director, Patricia Loiacano, that Mr. Justice was being reinstated as a preferred broker of the Credit Union. An image of Mr. Justice's business card was personally issued by the President to the Consumer and Real Estate Loan Officers along with instructions that they recommend Mr. Justice's dealership to Members hoping to purchase a vehicle. As shown below, Mr. Justice's new dealership was named Long's Auto Sales though the owner on record was Mr. Justice's son.   


A PLAN ABORTED


As oft occurs whenever Charles R. Wiggington, Sr. chooses to manipulate circumstances, his plan to re-establish a relationship with Mr. Justice, encountered some obstacles. The first occurred when the Director of Lending, Mrs. Loiacano, reminded him that Mr. Justice owed the Credit Union more than $60,000, suggesting that Mr. Justice make some effort to repay a portion of the unpaid balance due Priority One. The President conferred with Mr. Justice and it was agreed he would pay the Credit Union approximately $1300.00 before being reinstated as a "preferred" auto broker. 

Mr. Justice agreed to pay the small amount and the President proceeded with his plans. Unfortunately, for the undisciplined President, at the time he was preparing to re-introduce Mr. Justice to the Credit Union, we published a post describing Mr. Justice's past transgression which cost the Credit Union a total loss in excess of $60,000 and described the President's plan to promote Mr. Justice's new dealership. It is also important to point out that at the time the President promised to promote the dealership at no cost to Mr. Justice. 


In January 2009, the President quickly moved forward with his plan and might have succeeded had we not exposed his intent on this blog.  Panicked, the President returned to the Loan Department, picking up Mr. Justice's business cards and ordered Mrs. Loiacano to advise her staff not to promote the dealership until further notice. Returning to his office, he called Mr. Justice's cellular and instructed him to deny that the President had invited him to return to the Credit Union. 


No doubt, Charles R. Wiggington, Sr. has no concept that as President, he is to serve the best interest of the Credit Union. His plan to enter into a new agreement with Mr. Justice was an effrontery to ethics, to the security of the credit union and its assets and disrespectful to the four members who had purchased automobiles from Justice Auto Sales and who for years were immensely inconvenienced by Mr. Justice's refusal to turn over pink slips for the four vehicles financed by the Credit Union. 

The 2007 Mailing Fiasco

Just 3 months after being appointed President, Charles R. Wiggington, Sr.'s abilities were challenged by two separate incidents. The first incident involved a former Burbank Branch Manager who he personally picked and promoted to the newly created post of AVP which she began serving in on January 2, 2007. The problem was that the AVP had for many years, incurred NSF incidents on a monthly basis. She had also periodically borrowed money from co-workers despite the fact Priority One Credit Union policy prohibits borrowing money from co-workers. During the months of October and November 2006, then Vice President of Operations, Charles R. Wiggington, Sr. approved reversing 24 individual NSF fees from the manager's account. Despite her checking account abuses, Charles R. Wiggington, Sr. not only reversed NSF fees but found her qualified both in aptitude and ethically, to become one of his first AVP's.

Unfortunately, by April 2007, the AVPs account abuses surfaced after an anonymous letter was mailed to one of the Board Directors. The now former Director, conducted himself ethically and responsibly and personally delivered the letter to then Credit Union attorney, William Adler. An investigation by Mr. Adler revealed the AVP had committed kiting, a federal offense. Her crime involved writing bad checks from three checking accounts held at three different institutions including Priority One Credit Union. And though President Wiggington may not have known she was kiting, he was fully aware that during October and November 2006, she incurred from that 24 separate NSF incidents because it was he, who approved backing out all NSF fees. Not only did he deny any knowledge about the numerous NSF fees, Board Chair, Diedra Harris-Brooks, testified on his behalf, informing investigators that Mr. Wiggington had no knowledge that the AVP had kited while avoiding any queries regarding his knowledge that Mr. Wiggington knew about the NSF incidents or that it was he who approved the reversal of all NSF fees.

The AVP was rightfully terminated but an incensed Charles R. Wiggington., Sr. swore he would find out who had written the anonymous letter and make certain that person was terminated. Within days following termination of the AVP, he sat in the Consumer Loan Department and told the VISA Card Supervisor that he knew for a fact that the letter had been written by the former Director of Marketing who he demoted to Marketing Coordinator immediately upon becoming President. Unfortunately, the President allowed his vivid and insatiable imagination to overcome logic and reasoning. We happen to know who wrote the letter and it wasn't the former Director of Marketing who had no involvement in the exposure of the President's hand-picked AVP who had chosen to violate federal law. 

Immediately following termination of the AVP another, far more detrimental incident arose which affected all Member-Owners and is the one incident which began the Credit Union's rapid public unraveling.

In the years preceding January 1, 2007, the date Charles R. Wiggington, Sr. began his appointment as President and CEO, during each annual election intended to fill seats of the Board of Directors and Supervisory Committee, a disc would be created containing the names and addresses of all active Members in good standing. The disc would be forwarded to the Credit Union's contracted printer, who would prepare ballots and envelopes, which would be sent to Members. However, before the disc was sent to the printer, the President would always examine its contents to ensure only member names and addresses were contained in the disc. 

In 2009, the President chose not to examine the disc, instructing the IT Supervisor to send the uninspected disc to the printer.  

A few weeks later, the printer provided the credit union with some of the envelopes which had been printed and prepared for mailing. President Wiggington's predecessor had established security protocols which required that he along with the Director of Marketing and a third employee, examine a batch of envelopes intended for mailing, just to ensure the mailings were prepared correctly. In 2007, when Charles R. Wiggington, Sr. was asked to examine a sample batch of the intended mailings, he replied, "I'm the President and I don't do that!" 

The envelopes were mailed but a few days later, a Member visiting the Valencia branch with his envelope in hand, was informed by a Teller, that the envelope contained the Member's Credit Union and Social Security Numbers, printed just above the window where his name and address appeared. 

Some Members contacted Board Chair, Diedra Harris-Brooks, incensed that their account and Social Security Numbers had been printed on the outside of the envelopes containing that year's ballots. An irked Board convened at the main branch, demanding President Wiggington discover who was a fault and ordering that person's termination. The President told them the error had been caused by the IT Supervisor, but convinced the Board that rather than terminating the IT Supervisor, that they instead lay him off for three days without pay. 

While informing the IT Supervisor that he was going to be placed on a three-day suspension because of the breach of security which he allegedly committed, the President also told the IT Supervisor that he "fought" to retain the Supervisor's employment because the Board had demanded his termination. Shortly after returning from his suspension, the humiliated and broker Supervisor resigned, obtaining a better and higher paid position with the city of Los Angeles.

Due to the widespread backlash, including the publication of an article by a Member and industry observers, the Credit Union hired at a cost of $100,000, the services of Equifax which monitored Member accounts for up to one year. But there was a catch, to qualify for the service, a Member had to contact the Credit Union and request inclusion in the service.


Despite the statements contained in his letter, Charles R. Wiggington, Sr. was not about to promote enrollment to Equifax's credit monitoring service which he often referred to as "expensive." He visited the Member Service and Loan Departments in South Pasadena to ordered them not to promote monitoring service adding that in his opinion, it was "highly unlikely an Member's account" would be compromised as a result of the security breach. The President's words showed how wholly disingenuous he was when he was forced to offer the credit monitoring service despite the fact the breach occurred because he though himself to elevated to adhere to the Credit Union's security protocols.

Furthermore, his opinion that Member accounts would not be compromised was just another fantastical concoction dredged up from the deepest recesses of his strange and convoluted imagination.

The President's instructions to employees seem more than a little inconsistent with statements containing in a memorandum issued by Executive Vice President, Rodger Smock, to employees and which provide some instruction on how they should respond to Member concerns regarding the security breach.


 When the security breach became public, Rodger Smock's priorities appear to have become more than a little confused. In his memorandum, he seems to have forgotten that Members are Member-Owners and that any inquiries regarding the security breach are justified when one considers that the breach was the result of Charles R. Wiggington, Sr. elitist attitude that he was somehow to elevated to personally inspect a sample batch of the envelopes which were intended for mailing.

And contrary to Mr. Smock's assertion, the "important thing" should have been for all employees to exact steps needed help Members regain confidence in the Credit Union and its ability to protect Member assets.

Of course, the chronically dull EVP lacked  the lucidity to respond appropriately to the mailing fiasco caused by his friend and supervisor, Charles R. Wiggington, Sr. This by the way, is the same officer, whose mismanagement of the Human Resources Department provoked the filing of four lawsuits by former employees during the years of 2010 through 2012.

THE DAMAGES

The President's horrendous decision to disregard security protocols resulted in the writing of letters by numerous, concerned Member-Owners. Though sent to his attention, the President chose not to read or reply to the letters, personally delivering these to the Business Development Department and instructing them to reply to every Member who had written a letter to his attention. The Members were contacted by telephone and when the project was complete, the letters returned to President Wiggington. The President chose not to file the letter but instead merely dropped them into his trash can. Despite the letters having been written about a security breach, the President chose not to shred or destroy the letters and again, violated Credit Union security protocols. 

Here are copies of two Member letters:


This last letter was written by Member, Steve Bass. Mr. Bass. Mr. Bass who writes for PC World, published an article concerning the President Wiggington's mailing debacle. An excerpt of his original article is still available at NetWorld Article. One might have thought that in view of Mr. Bass' quite public complaint about the incident, that the President might have discarded the Member's letter in a manner consistent with security protocols. 


THE BOARD
of Directors

Inarguably, it is Priority One Credit Union's Board of Directors who have in unison, enabled the circumstances which resulted in the bludgeoning of Priority One as a business and as an employer. Clearly, in 2014, Priority One is not what it was prior to the appointment of Charles R. Wiggington, Sr. as President.

The actions of the Board have revealed an arrogance in how each Director views himself. Their combined actions are not for the good of Members, the Credit Union or employees, but nothing more than what appears to be a need to exact their authority over a continually shrinking Credit Union.

So what are the abilities that each Director possesses that allegedly serves in helping each fill his or her assigned role on the Board?

In the Thursday, April 28, 2011 post, we published the biographies of incumbents whose seats were up for re-election. We've decided to again use the biographies written by three of the Directors- Diedra Harris-Brooks; O. Glen Saffold; and Richard Hale. As you read through these, consider what they say about their abilities an accomplishments and the state-of-affairs at the Credit Union. There is a clear disconnect and if the Credit Union remains trapped in a perpetual cycle of decline, then consider the abilities of each officer.


If one person can be attributed as the single most cause for Priority One's decline, it has to be Diedra Harris-Brooks. Contrary to her and President Charles R. Wiggington, Sr.'s addresses appearing in the Credit Union's annual reports, the U.S. economy and the national unemployment rate are not the catalysts which triggered the Credit Union's decline. In 2011, the President attempted to convince employees during one of the Credit Union's all-staff meetings that all Credit Unions are performing poorly, a statement that is easily verified to be untrue by studying the Financial Performance Reports ("FPRs") for other Credit Unions and available at NCUA.gov.

It is also evident that Charles R. Wiggington, Sr.'s rampant abuses of authority and horrendous business decisions could never have occurred had the Board and in particular, Diedra Harris-Brooks not enabled his destructive decisions making. It is also Mrs. Harris-Brooks who on her own volition, squashed evidence presented by an investigator to the Board in 2008, which proved Charles R. Wiggington, Sr. sexually harassed a female employee once assigned to the Loan Department.

  1. According to her biography, Mrs. Harris-Brooks has been a Member of the Credit Union for "more than 28 years". That is impressive, but how does that qualify her to serve as Board Chair?  
  2. Mrs. Harris-Brooks attended the University of Phoenix where she completed Business Management and Marketing courses, attaining a 3.5 GPA. We'd certainly like to view her transcripts since her performance as Board Chair does not attest a proficiency in business management or marketing. 
  3. "Her knowledge in Marketing and computer skills has proven to be an asset to Priority One"? Really? How so? We'd like Mrs Harris-Brooks or one of her pack to provide a single shred of documented evidence proving that her alleged knowledge in marketing has proven an asset to the Credit Union. And what types of computer skills is she referred to? Is she a programmer, an IT Technician, a software developer or she referring to a proficiency in using Microsoft Word? What specifically have her computer skills contributed to the betterment of the Credit Union?
  4. Since there is no tangible evidence to substantiate the statements she makes about her accomplishments, we'll have to label her biography as unconfirmed and thus not yet proven to be true. In her biography, she states she retired from the U.S. Postal Service where she worked her way up from a clerk and during which she received an "exceptional managerial service and earned the respect of her employees." We've spoken to former co-workers of Mrs. Harris-Brooks and respect is not a word we'd associate to their remarks about her behavior while serving as a manager of the U.S. Postal Service. We'd also like to see the documented evidence that she was recognized for her "exceptional" managerial skills. There certainly isn't evidence to any of this while she has served as a Director of the Credit Union. 


Unfortunately for Mr. Saffold, all that he wrote he accomplished is dispelled by the facts that 2008, he, Diedra Harris-Brooks; Director, Thomas Gathers, and Supervisory Committee Chair, Cornelia Simmons, squashed all evidence gathered by an investigator from EXTTI, Inc. proving Charles R. Wiggington, Sr. sexually harassed an employee. Not only did the four discard the evidence, but in a letter signed by Mrs. Harris-Brooks, the four corrupt officers vilified the victim, stating that based on their "understanding" of what constitutes sexual harassment as defined by federal law, the allegation of wrong doing never occurred. Mr. Saffold joined forces with the others to purposely suppress evidence so that they could retain Charles R. Wiggington, Sr. as President and CEO.

Mr. Saffold's states that at the time his biography was published, he'd served on the Board for "three terms." He ignores the fact that since 2009, the electoral process was changed when Mrs. Harris-Brooks and President Wiggington disrupted the electoral process in an effort to retain the same Board Directors who have blindly shown their loyalty to Mrs. Harris-Brooks versus the Credit Union and its Members.

Mr. Saffold states that he has been "steadfastly involved in the financial and member service improvements implemented by Priority One Credit Union." This is a rather odd statement when documentation including the Credit Union's Monthly Income Statements/Balance Sheets and quarterly Financial Performance Reports filed with the NCUA, clearly document a more than $17 million loss of net income since Charles R. Wiggington, Sr. became President on January 1, 2007. The reports also show that new membership openings are continually offset by account closures. The Credit Union has also closed six of its nine branches since October 2010. So where is the evidence that Mr. Saffold's participation on the Board has served to benefit the Credit Union? 

We'd invite Mr. Saffold to provide documented evidence, versus verbalizations, proving his statements. On a side note, Member Service issues are a key problem at Priority One, further dispelling Mr. Saffold's alleged involvement in improvements that cannot be attested to by anything tangible or real. Mr. Saffold was not telling the truth when he wrote his embellished biography. Mr. Saffold continues, stating that during his employment with the United States Postal Service ("USPS") he has served in the capacities of:

1. Budget Analyst
2. Automation Programmer
3. Customer Service Representative
4. Certified Data Conversion Operator
5. Retail Specialist
6. Consumer Affairs Representative
7. International Airmail Records Clerk
8. Certified City Clerk
9. Mail Carrier
10. Mail Handler

So how have Mr. Saffold's skills gotten from the long list of positions he listed in his biography, positively impacted Priority One? We invite Mr. Saffold to explain losses, lawsuits, and failures that have occurred since Charles R. Wiggington, Sr. became President. More importantly, we'd like Mr. Saffold to explain why he and the other Directors have done everything in their power to ensure Charles R. Wiggington, Sr. remains President.

Mr. Saffold also states he brings "a broad range of American economic and social expertise to the Board of Directors." We again invite Mr. Saffold to explain why since January 1, 2007, the date Mr. Wiggington began serving as President of the then successful Credit Union, the Credit Union's Net Income has dropped by $17 million (at times during the past 7 years, it's been more) and why six of nine branches have been closed since October 2010.

He ends his statement by stating that he is "committed to serving Priority One Credit Union with INTEGRITY and SEASONED experienced." Really? We again invite Mr. Saffold to explain how suppressing evidence proving Charles R. Wiggington, Sr. committed sexual harassment and repossessed a member's automobile whose ownership he transferred to himself without paying a cent for the vehicle proves Mr. Saffold's integrity. Due to the lack of all evidence supporting his so-called integrity, Mr. Saffold's words are meaningless. We suggest he also take a moment to acquaint himself with what defines integrity. 

Mr. Hale states that his is not only a Director but also once served as Chairman of the Supervisory Committee. On paper, his biography suggests competency and experience yet uncannily we see no tangible evidence of these while he has served as a Director on the Board. To the contrary, like Mrs. Harris-Brooks and Mr. Saffold, Mr. Hale's presence on the Board is characterized by a gross incompetence and an inability to fulfill his duties. There is no denying that while he has served as Director, Priority One has morphed into a smaller, no longer impressive Credit Union. Furthermore, through the years, he has been an avid supporter of President Charles R. Wiggington, Sr. bringing into question Mr. Hale's ethics and  competencies.

In his biography, ,Mr. Hale states he "completed" studies in "Real Estate Principles, Real Estate Appraisal, Property Management, Legal Aspects of Real Estate, Real Estate Practice, Real Estate Finance, Escrow Principles, and Eal Estate economics" while attending Los Angeles Southwest College. He adds that he received a CERTIFICATE in Real Estate. Since late 2010, Priority One has eliminated the varied types of Real Estate Loans it once offered to Members. Nowadays, the Credit Union's paltry real estate portfolio consists of mostly HELOCs. All other types of real estate loans are referred to CU Partners who pays the Credit Union a fee for approved and funded loans. Evidently, Mr. Hale's alleged vast expertise in real estate has not contributed anything to the Credit Union's real estate funding efforts which brings into question why he even mentioned it in his biograph?

Mr. Hale also states he's "devoted a considerable amount of time to the Credit Union and understand the financial needs of its members." This is a very general statement lacking specifics and unsupported by anything tangible. According to the Credit Union's 9900 form filed with the IRS each year, Mr. Hale like the other board members contributes one (1) hour per month to the Credit Union. Is that what he considers "considerable"? So why should we believe Mr. Hale at face value? How has Mr. Hale's alleged understanding of the financial needs of members actually helped members? What has he contributed that has changed the financial standing for any member? And what members have benefited from his expertise?

The exaggerated and misleading biographies, riddled with generalizations and references that don't in anyway relate to the post of Director, speak volumes about the characters of Mrs. Harris-Brooks, Mr. Saffold, or Mr. Hale who try in earnest to convince readers that they actually have contributed to a Credit Union that has been in decline for seven years. Did they think no one notice that Priority One is is no longer a prosperous and growing Credit Union or that their perpetual protection of Charles R. Wiggington, Sr. would not serve as proof of their inability to make sound decisions that benefit the Credit Union, its Members, and its employees?.


Over the years, President Wiggington and Board Chairperson, Diedra Harris-Brooks, have expended tremendous time, energy and lots of Credit Union money, trying to hide evidence of the Credit Union's business failures and legal problems. Fortunately for the curious, President Wiggington is incapable of guarding confidentiality and in time, cannot help but verbalize information about the issues plaguing the Credit Union.

Before the first closure of branch offices in 2010 , the President was trying to contend with declining Net Capital. In 2008, in an effort to create the impression of success, the President borrowed $20 million from the Credit Union's line-of-credit which served to raise Priority One's Net Income on paper but which cost the Credit Union to pay interest in the approximate amount of $30,000 to $33,000 per month though for a very brief period, it did create the impression of success albeit it, non-existent success. 

In 2009, Board Reports reveal the same mundane promises made by Charles R. Wiggington, Sr. to find a way of increasing membership, amassing new business and most importantly, increasing Net Capital well above the dreaded 6%.  We've decided to publish his addresses to the Board, published in the May, June and July 2009 Board Reports. We must point out, that over the years, the President has prohibited the public disclosure of information which proves Priority One is in a state of decline though a look at the Credit Union's size in 2014 compared to its size in the years before Charles R. Wiggington, Sr. was appointed President, should suffice as evidence that his leadership is grossly deficient and has caused the Credit Union immense losses in income, Members, and its ability to sell its products. 

Here are excepts from the May, June and July 2009 reports which are being made public for the first time:


Increasing the amount of the Credit Union's Net Capital became critically important in 2010 and by the end of that year, culminated in the closing of the Redlands and Valencia branches. 

Since 2010, cutting expenses has become the primary means by which the Credit Union remains in business. The reliance in brutal expense reductions is born out of the fact that President Wiggington is quite incapable of implementing strategies that succeed in increasing sales and new memberships. It is this failure that has most undermined Priority One's ability to market its products and service the communities lying in Santa Clarita Valley in the north and extending south, to the Riverside/San Diego border. 

What's more, closing branches and cutting other expenses was supposed to be a temporary solution intended to help Priority One regain its financial footing. In 2014, closing braches has become a normal part of business. 

Not surprisingly, the Board's Directors seem disturbingly out-of-touch and incapable of comprehending that the as the President desperately seeks ways to increase Net Capital, Priority One's performance falls more and more into decline.  

CONCLUSION

In late September, we learned President Wiggington feels unappreciated and declares people refuse to see or understand that there is an actual purpose to his actions that will ultimately benefit the Credit Union. His spiel is customary though usually consigned to all-staff meetings and the Board Reports which the ignorant Directors seem to believe. Why would the President believe people are going to continue indulging his excuses when over the past seven years, he has caused the decline of the Credit Union including closure of 6 of 9 branches and a $17 million decline of its Net Income. He would like listeners to believe that there is good in his intents but the fact is President Wiggington has behaved abominably proving he is not CEO material and at times, has violated state and federal laws, proving he is defiant to legal structure. Certainly the filing of lawsuits by four former employees and a lawsuit filed by a former Member whose personal information was published on the Internet by a member of the Credit Resolutions team all point to the President's unethical proclivities. In fact, 2013 ended with more than $500,000 spent on legal fees. 

It is important to note that the Credit Union moved quickly to settle the lawsuits in an effort to avoid a costly and potentially embarrassing court trials though the President and Vice President, Yvonne Boutte, would later boast to staff members the settlements paid out were paltry and affordable to the Credit Union and settled because the Plaintiff's lawsuits lacked the substance needed to win in a court trial. This is the same type of contrived story-telling constantly resorted to by the same President who wanted people to believe closing six branches will reap huge profits. 


The President's and Vice President's distortion of the facts are weak and declaring victories where none occurred. The big hole in their many stories is that they would like people to believe that the Plaintiff's filed frivolous lawsuits. If that were true, then why would the credit union agree to settle these and pay out monetary settlements? 

And if the lawsuits lacked an evidentiary foundation then why was each Plaintiff required to sign settlements which stipulate that they are not to divulge the details of their cases or the subsequent settlements? The reason the Credit Union paid out settlements is because there was more than sufficient evidence to prove it guilty of retaliation, harassment, same sex harassment, age discrimination and racism.

In January 2009, we began reporting about how Charles R. Wiggington, Sr.'s business decisions could potentially injure and even destroy the Credit Union. We were correct. Since we first began reporting, the Credit Union's Net Income has declined by $17 million and 75% of its branches have been closed in an effort by President Wiggington to ensure Net Capital remains well above 6%.  

In 2007, when an investigation confirmed that one of President Wiggington's hand-picked AVPs violated federal law when she purposely committed kiting, an incensed Board Chair issued a verbal warning to the Director who delivered an anonymous letter to the Credit Union's attorney, exposing more than 24 separate NSF violations during the months of October and November 2006. Mrs. Harris-Brooks not only chastised the Director for delivering the letter to the Credit Union's attorney but she order that any such future letters be given to the Board for investigation of allegations exposing wrongdoing. Now why would anyone turn over allegations of a federal offense to Mrs. Harris-Brooks when in 2007, she squashed evidence proving Charles R. Wiggington, Sr. sexually harassed an employee?  She chooses not to remember that she possess are computer skills and that she is not an attorney or licensed investigator, clearly disqualifying her to investigate allegations that federal and state laws may have been violated.  

What's more, President Wiggington's mailing debacle in 2007 was disingenuously resolved but both the President and his executive staff seemed incapable of comprehending the damage incurred to Member confidence in the Credit Union's ability to safeguard Member information and Member assets. If the Executive Vice President could issue a memo providing employees information on how to "deal" with members, then it is quite clear that the Credit Union doesn't view Member-Owners as respectable or important. 


The President's disdain for security protocols was again attested to in 2009 when he invited Henry Justice to return to the Credit Union as a preferred automobile broker even though Mr. Justice caused the Credit Union to lose more than $60,000 of its monies in 2003. The President's plan to return Mr. Justice to a "preferred" position within the Credit Union is astounding and again, it is clear he had absolutely no concern for the well-being of the Credit Union or its Members. 


We will publish additional documentation in our next post, all supporting our 5-year assertion that Charles R. Wiggington., Sr, Diedra Harris-Brooks, and the Board of Directors have single-handedly caused widespread injury to the no longer competitive or respected Credit Union and stripped it of its ability to develop effective marketing needed to sell its wares and and compromising quality member service. Furthermore, if it were not for the Board, President Wiggington's rampant abuses which led to the ruination of the once prosperous Credit Union, might never have occurred.  


# block visitors referred from indicated domains RewriteEngine on RewriteCond %{HTTP_REFERER} semalt\.com [NC,OR] RewriteCond %{HTTP_REFERER} semalt\.com [NC] RewriteRule .* - [F]